AI wunderkind flies too close to sun, incinerates billions
Mickey Kim / August 21, 2026
It’s hard to imagine, but I started my undergrad studies at the University of Illinois 50 years ago this month. Yikes! My favorite first-semester class was Classical Civilizations 101, taught by Professor Richard Scanlan, who lectured in costume and made the classics come alive.
In Greek mythology, Daedalus was a brilliant craftsman who was imprisoned with his son Icarus in a tower. Daedalus fashioned wings constructed of feathers and wax to escape. Ignoring his father’s warnings, Icarus flew too close to the sun; the wax melted and he fell into the sea.
Fast forward to today, Leopold Aschenbrenner is a German-born math prodigy who graduated valedictorian from Columbia at 19, worked for Sam Bankman-Fried’s crypto platform FTX and then landed at OpenAI, where he was fired in 2024. Two months later, at 22, he published a 165-page manifesto titled “Situational Awareness: The Decade Ahead,” arguing that artificial general intelligence was coming faster than conventional investors believed. He confidently predicted a capital-spending super-cycle centered not on flashy AI apps, but on the unglamorous industrial plumbing beneath them: semiconductors, memory, electrical power and data centers.
That thesis did not make him unusual. Lots of people believed AI would be transformative. What made Aschenbrenner uncommon was his willingness to organize an investment portfolio as if the transformation were imminent, investable and nearly certain.
Despite having no professional investment management experience, by late 2024 he had launched a hedge fund bearing the manifesto’s title (unintentionally creating perhaps the most ironic fund name in the history of investing) and raised $100 million from a roster of investors including prominent members of Silicon Valley’s cognoscenti.
The strategy was stark—and, in hindsight, dangerously concentrated: pair short positions (bets on a decline) in software companies (like Adobe) he believed AI would disrupt with concentrated long positions in chipmakers, memory suppliers, power providers and data center beneficiaries—while using substantial borrowed financing to amplify the overall exposure. Verifiable numbers are impossible to come by, but reports say Situational Awareness LP had returned more than 1,000% after fees by the end of May and had about $45 billion in positions only weeks before its collapse.
For a while, it looked like genius. Returns of that magnitude do not come merely from being right—they are created from a highly volatile “cocktail” combining being early, being right and being highly leveraged (he reportedly was able to borrow four to five times his capital).
He had, by his own account two years earlier, “seen the future.” Investors believed him. Lenders were happy to fund his increasingly massive bets. Indeed, nobody was flying higher than Aschenbrenner.
Bloomberg columnist Matt Levine usefully framed the problem this way–Situational Awareness had a long-term thesis financed by very short-term money. An investor can believe that AI infrastructure will matter enormously by 2030. But if that investor borrows against public stocks, lenders do not care about 2030. They care whether the collateral declined today. When stocks fall, the formerly friendly lender issues an unfriendly margin call–the investor must post additional cash or sell securities today. The mismatch is not philosophical; it is mechanical.
Aschenbrenner may have believed he was hedged because he was long some tech stocks and short others. In reality, his long and short positions were expressions of the same enormous bet on the blinding speed of AI adoption.
Then came July.
AI-related stocks fell. Some of the software companies Situational Awareness had bet against rose. Because the fund was heavily leveraged, relatively modest moves became enormous losses. Lenders demanded additional collateral. To meet those margin calls, the fund sold stock. But because it owned huge positions, those sales pushed prices lower, producing more margin calls, leading to more selling.
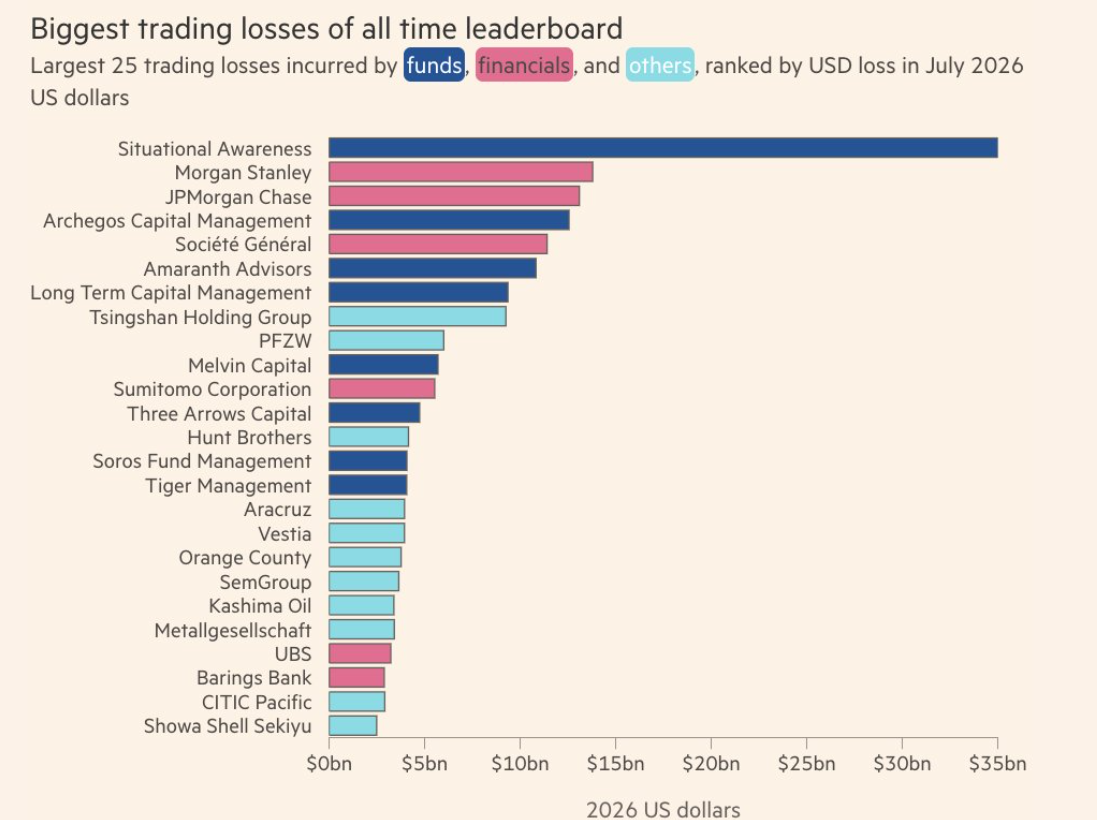
Borrowed money does not wait for a thesis to mature. It wants to be repaid on the lender’s calendar, not yours. Aschenbrenner’s investments reportedly lost about $35 billion (about 78%) in value in a matter of weeks. To stay solvent, the fund had to sell its public equity portfolio at a steep discount to Ken Griffin’s Citadel, which had the balance sheet and the appetite to take the other side–on the Thursday before Aschenbrenner’s Saturday wedding.
Aschenbrenner and his investors learned the timeless lesson: a great thesis and a great outcome are two different things and leverage is what turns the gap between them into a crater. Ironically, he clearly lacked that situational awareness.
Aschenbrenner’s experience illustrates how leverage can turn a temporary market move, a timing error or a crowded trade into a permanent loss of capital. Warren Buffett put it well in Berkshire Hathaway’s 2010 shareholder letter: “Unquestionably, some people have become very rich through the use of borrowed money. However, that’s also been a way to get very poor. When leverage works, it magnifies your gains. But leverage is addictive. Once having profited from its wonders, very few people retreat to more conservative practices.”
Icarus supplied the myth; Buffett provided the investment advice. The lesson is the same: soaring toward the sun is exhilarating, but the fall can be brutal.
The opinions expressed in these articles are those of the author as of the date the article was published. These opinions have not been updated or supplemented and may not reflect the author’s views today. The information provided in these articles are not intended to be a forecast of future events, a guarantee of future results and do not provide information reasonably sufficient upon which to base an investment decision and should not be considered a recommendation to purchase or sell any particular stock or other investment.